Australia’s mortgage buffers may be softening some of the immediate pain from higher interest rates, but that doesn’t mean monetary policy has lost its punch, according to Reserve Bank of Australia Assistant Governor (Financial Markets) Christopher Kent.
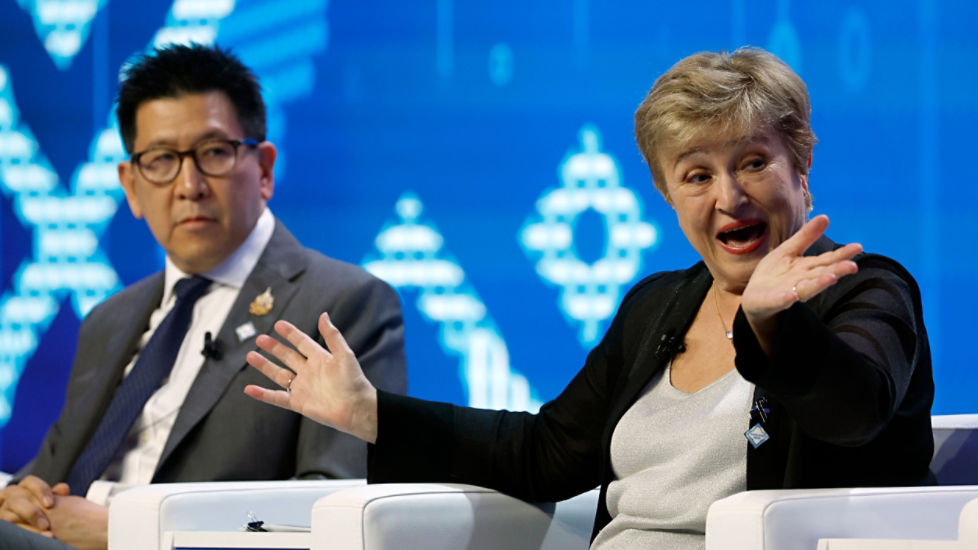
In a wide-ranging conversation with Commonwealth Bank Head of Australian Economics Belinda Allen at Commonwealth Bank's Global Markets Conference in Sydney, Kent said there was no reason to think the potency of monetary policy had “changed dramatically one way or another”.
The important mechanisms through which interest rates affect the economy were still operating, he said, including the exchange rate, housing and household wealth, saving decisions and the direct impact of higher borrowing costs.
The harder question for the RBA is whether current financial conditions were restrictive enough, Kent said.
Mortgage buffers don’t tell the whole story
The direct impact on mortgage holders is the most visible way higher interest rates affect households, but Kent said the "cashflow channel" - that is, the way monetary policy affects the amount of disposable income Australian households have available to spend - can get also get too much attention.
Large balances in mortgage offset accounts can reduce the effect of rate rises on some borrowers’ cashflow. But Kent said that was partly the point of those buffers.
“That’s true. But that’s by design. Australian households pay the mortgage down a bit faster, and it’s a way of providing better self-insurance,” he said.
Higher rates also encourage people to save more or repay debt faster rather than spend now, while falling asset prices can affect household wealth and spending.
But Kent said there was no evidence the cash-flow channel itself had changed significantly.
Why the Australian dollar matters
The Australian dollar is another important part of the story.
Kent rejected the suggestion that the Aussie dollar’s recent resilience had made monetary policy less effective, describing a flexible exchange rate as a useful stabilising mechanism for the Australian economy.
Higher Australian interest rates can support the dollar relative to where it would otherwise be, which can lower the Australian-dollar cost of imported goods.
That can matter even when inflation is being driven by a global shock such as higher oil prices, Kent said. Australians ultimately pay for fuel in Australian dollars, meaning a stronger exchange rate can reduce some of the local price impact, he said.
Kent said the exchange rate was one of the channels that tended to be overlooked when debate focused heavily on mortgage repayments.
Kent said the currency’s resilience may also reflect Australia’s appeal as a place to raise capital. The country’s relatively sound fiscal position, well-regulated markets and deepening financial system have supported growing bond issuance from both domestic and off-shore, or "Kangaroo", borrowers, while greater issuance can improve market liquidity and reduce hedging costs for Australian banks raising funds offshore.
“Australia is now an attractive place to issue and raise funds. That’s a really positive development because it deepens our financial markets and helps reduce the cost of hedging for Australian banks,” Kent said.
What does the ‘neutral rate’ tell us?
Kent said a key starting point for the RBA is the neutral interest rate, the theoretical cash rate that neither stimulates nor restrains the economy.
The problem is that neutral can’t be observed directly and estimates come with considerable uncertainty.
Kent said the current cash rate and the expected path for rates sit towards the upper end of the RBA’s range of central neutral-rate estimates.
“That tells you that you have some confidence that monetary policy is somewhat restrictive. But the question is: is it restrictive enough?”
There are also competing forces affecting where neutral may sit.
Large investment cycles, including spending on AI infrastructure, and government spending decisions could put upward pressure on neutral rates. Meanwhile, ageing populations and questions over longer-term productivity growth could pull in the other direction.
Kent said that made neutral an important starting point rather than a precise guide to where monetary policy should be set.
Are CGT and negative gearing changes having an impact?
Housing is providing clearer signs that tighter financial conditions are having an effect.
Kent pointed to weakening housing credit growth, softer house prices and housing turnover, and weaker forward indicators for dwelling investment.
Recent tax changes affecting property investors were also working in a similar direction as monetary policy.
Asked whether those changes had effectively done some of the RBA’s inflation fighting work, Kent said it was difficult to separate the effects, saying only that “it’s moving in the same direction as monetary policy”.
However Kent said the fall in property investor lending was one of the larger moves seen during recent tightening phases and was “no doubt” partly due to the tax changes and their effect on investor incentives.
Labour market may be changing gears
The labour market is also showing signs of slowing.
Allen pointed to the latest unemployment rate of 4.7%, asking whether conditions could be loosening - meaning more potential employees are available for employers to hire - more quickly than expected.
Kent cautioned against putting too much weight on any single monthly result, particularly given changes to the labour force survey.
But he acknowledged there were indicators suggesting the labour market had become less tight faster than the RBA had forecast.
The RBA would need to consider that alongside the upcoming inflation data, he said, to judge whether softer employment conditions reflected weaker demand and what that meant for inflation pressures.
Why rate rises take time to work
Complicating the picture is the time it takes for changes in interest rates to flow through the economy.
Kent said monetary policy operates with “long and variable lags”, making it difficult to know in real time how much of the effect of previous rate rises is still to come.
The RBA uses economic models and closely watches the early stages of monetary policy transmission to judge whether higher rates are behaving as expected.