Why AI adoption alone won’t solve Australia’s productivity problem

AI is being rapidly adopted by Australian business, but leaders at CommBank’s Accelerate AI event say the bigger economic payoff will depend on redesigning work, lifting productivity and making sure workers are part of the journey.

18 November 2026

(Left to right) Commonwealth Bank CEO Matt Comyn, Origin Energy CEO Frank Calabria, Telstra CEO Vicki Brady and  Wesfarmers CEO Rob Scott join moderator Jeni Whalan for the CEO panel at CommBank Accelerate AI in Sydney. Picture: Nic Long.

Key points

  • AI adoption has surged, but productivity gains have yet to follow.
  • Higher productivity is critical to lifting real wages and living standards.
  • Business leaders say redesigning work, building skills and investing in infrastructure will be key.
  • Panels featuring Productivity Commissioner Danielle Wood, e61 Institute CEO Michael Brennan, CommBank Chief Economist Luke Yeaman, Telstra CEO Vicki Brady, Wesfarmers CEO Rob Scott, Origin CEO Frank Calabria and CommBank CEO Matt Comyn discussed the impact of AI on business and the economy.

Australia’s challenge is no longer simply adopting AI, but turning its rapid uptake through businesses into higher productivity.

The next phase of AI will be less about whether the technology is being used and more about how deeply organisations are prepared to change around it, business leaders told Commonwealth Bank’s Accelerate AI event in Sydney.

CommBank Chief Economist Luke Yeaman said productivity was fundamental to improving real wages and living standards.

“The one thing in economics we know fundamentally is that the surefire way to increase real wages, to increase living standards, make people feel better, is to lift productivity,” Yeaman said.

The challenge, he said, was getting those benefits sooner.

“How do you bring it forward as much as possible? Make it two to three years, not three to five years,” Yeaman said.

The questions of why widespread AI adoption had yet to show up in Australia’s productivity figures, and what businesses needed to change for that to happen ran through multiple discussions at the event.

Opening the ‘Policy to Productivity’ panel, CommBank Executive General Manager Strategy Helen Mayhew pointed to the gap between the adoption of AI and the state of productivity in the country.

“Twelve months ago, when the Reserve Bank asked a selection of firms if they were using AI, about a third said that they weren’t. Twelve months later, almost no one says that,” Mayhew said.

But over the same 12 months, productivity in Australia fell, she said, and now sits at the same level it was at back in 2019. “So the technology has arrived, but it’s not showing in the numbers.”

Why isn’t AI showing up in productivity?

e61 Institute Chief Executive Officer Michael Brennan said history offered some clues about why the gains could take time to emerge.

Using the introduction of electricity into factories more than a century ago as an example, he said simply replacing steam power with electric motors delivered some savings. But the larger productivity gains came decades later when businesses reorganised production around what electricity made possible.

“It was the reorganisation that that sort of spurred the productivity growth,” Brennan said. “And that takes time. And it takes this kind of complementary innovation.”

He said AI could be at a similar stage, with workers widely using the technology to make existing tasks easier without it yet being deeply embedded in business systems and models.

Productivity Commission Chair Danielle Wood said the Commission’s estimate that AI could add around 4% to labour productivity over a decade was conservative, but deeper adoption would be needed to realise those gains.

“Most people are using it not actually for their core tasks. We haven’t fundamentally transformed our production processes and supply chains,” Wood said.

Her message to business was not to wait for the technology to settle.

“I’d love to see business kind of rediscover their animal spirits when it comes to AI adoption,” she said.

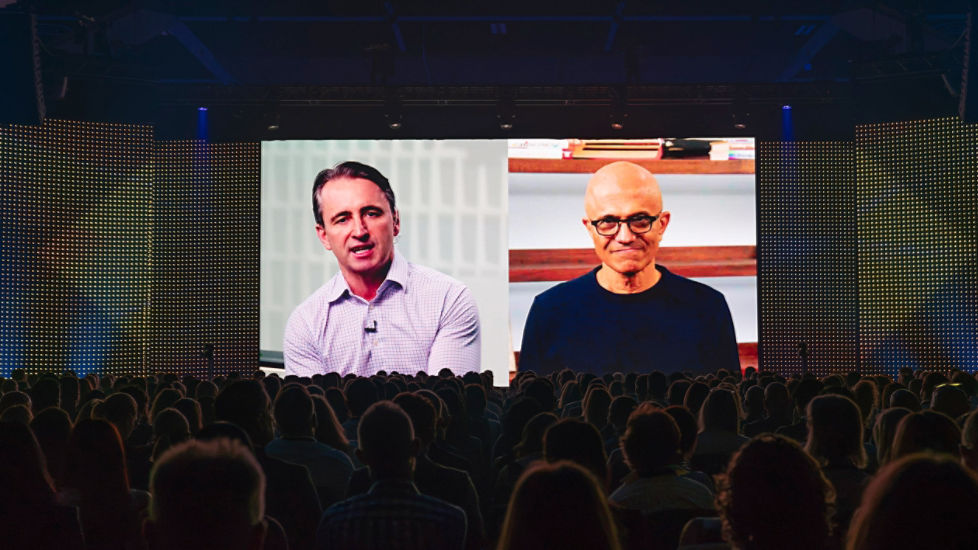
CommBank Chief Economist Luke Yeaman, Productivity Commission Chair Danielle Wood, e61 Institute CEO Michael Brennan and moderator Helen Mayhew discuss Australia’s AI productivity challenge at CommBank Accelerate AI in Sydney. Picture: Nic Long. CommBank Chief Economist Luke Yeaman, Productivity Commission Chair Danielle Wood, e61 Institute CEO Michael Brennan and moderator Helen Mayhew discuss Australia’s AI productivity challenge at CommBank Accelerate AI in Sydney. Picture: Nic Long.

From using AI to redesigning work

Later the event’s CEO panel picked up that question from the perspective of businesses already deploying AI across large workforces.

Moderator and CommBank General Manager Strategic Policy Jeni Whalan said the earlier discussion had shown that AI’s productivity potential would emerge as organisations reorganised work and underlying business models began to shift.

CommBank Chief Executive Officer Matt Comyn said businesses needed to make use of the period before more substantial workforce changes emerged.

“I don’t think it’s going to be hugely disruptive near term, but we have to use the time well,” Comyn said.

That included helping people understand their skills, gain practical experience and identify different roles and career paths.

Comyn said AI fluency was likely to become a broad skill across many job families, while new career paths would emerge as organisations changed how technology was used and decisions were made.

Telstra Chief Executive Officer Vicki Brady said the company had focused on giving employees access to tools and building AI skills, but was now beginning the harder task of redesigning the way work is done.

“The next thing we’re just stepping into now, which I think is fascinating, is a lot of talk about redesigning work,” Brady said.

“So in the context now of people and AI working side by side, how do you make it simpler for people? How do you get better customer outcomes? How do you unlock value from it?”

Wesfarmers Chief Executive Officer Rob Scott said its approach was “people first, digitally enabled”, with technology judged by what it delivered for workers and customers.

“If we can’t demonstrate how AI is going to help our customers or help our team, then we’re not focusing on the right things,” Scott said.

At Wesfarmers’ hardware business Bunnings, he said, a chatbot that gave team members access to technical and project information had already saved more than 30,000 hours.

Building the infrastructure for AI

The economic gains will also depend on infrastructure outside individual businesses.

Yeaman said AI investment was already adding demand to the economy through data centres, energy, construction and technology before the larger productivity benefits had arrived.

He said the bigger challenge was making sure those benefits arrived quickly enough to justify the investment and keep Australia competitive.

Origin Energy Chief Executive Officer Frank Calabria said AI was increasing electricity demand at the same time as the energy system was undergoing its existing transition.

“The number one thing we can do as a sector is to provide reliable and affordable energy on time,” Calabria said.

But Calabria said getting infrastructure built would also depend on communities sharing in the benefits.

“You actually have to demonstrate that you are a member of those communities, that you are genuinely contributing back to those communities,” he said.

Bringing people with the technology

Workforce confidence and public trust also emerged as important parts of the productivity challenge.

Scott said businesses had to be open about the uncertainty surrounding AI rather than pretending they could predict exactly how jobs would change.

“There’s so much uncertainty. No one can predict the future. So I think we need to be really transparent about that,” he said.

Wood said the technology industry also needed to take care with predictions about AI’s impact.

“What I would like the tech industry to stop doing ... is stop scaring the crap out of everyone,” she said.

Wood pointed to some claims that large number jobs could be lost within five years, saying such predictions made people uneasy and were “not a great way to build the kind of trust that we actually need to see in this technology to get the benefits from it”.

Telstra’s Brady said investment in people also had to keep pace with investment in the technology itself. “Yes, it is investment in technology, but it’s investment in our people, the capabilities,” she said.

The risk of waiting

Across both panels, there was broad agreement that Australia had time to manage the transition carefully, but could not afford to stand still.

Yeaman said countries that captured AI’s productivity benefits more quickly could pull away from those that did not.

“I think that’s how you make Australians feel poorer. Over time, if we don’t get these benefits and other countries do, we’re going to fall further behind,” he said. “People are going to feel that pressure in their wage packets and in their standard of living.”

Comyn said Australian businesses needed greater dynamism and a willingness to take risks as they worked out how best to use the technology.

“We need more dynamism. We do need more risk taking,” he said.

Brady said businesses also needed to act.

“We’ve got to work with real urgency here because the opportunity is there to grab and we’ve got to be bringing people with us,” she said.


CommBank’s Accelerate AI event explores how organisations are translating AI ambition into real business and economic value. Follow insights from Accelerate AI on the Accelerate AI event page.

Newsroom

For the latest news and announcements from Commonwealth Bank.

Things you should know

Media releases are prepared without considering an individual reader’s objectives, financial situation or needs. Readers should consider the appropriateness to their circumstances. Visit Important Information to access Product Disclosure Statements or Terms and Conditions which are currently available electronically for products of the Commonwealth Bank Group, along with the relevant Financial Services Guide. Target Market Determinations are available here. Loan applications are subject to credit approval. Interest rates are correct at the time they are published and are subject to change. Fees and charges may apply.