Help & support

It’s a big step for any relationship so before you decide if it’s right for you, you should:
Questions to ask your partner about money.
All couples manage their finances differently and while one way may work for some couples, it may not work for you. Here are some common ways joint accounts are used by couples:
Having a budget will help you manage your household expenses. Get started by mapping out what you each earn every pay cycle and how much you each spend during that time on things like:
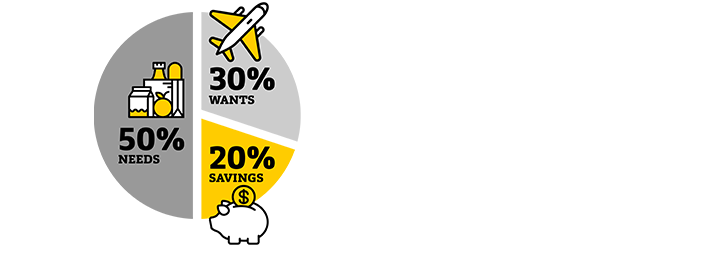
A good rule of thumb for budgeting your salaries is the 50-30-20 rule which helps you plan to pay bills (50%), add to savings (20%), and have money to spend on fun (30%). Get started with our budget planner tool or read more about how to manage your money with tech.
Once you’ve got your budget in place you can start saving for the next big thing. You may want to pool your savings together for something shared like a holiday or a house deposit, or you may want to keep your savings separate.
Start by setting yourselves a weekly or monthly savings goal that’s achievable and make sure you don’t dip into it when you feel like splurging.
It’s also a good idea to split your savings into different buckets, one for saving for the future and one for emergency savings in case the unexpected happens, like a broken washing machine or burst water pipe.
See how much you could save with our savings calculator.
Joint everyday account
Bank
Opening a bank account together can be a great way to pool your money and improve your household spending habits. With CommBank, this can be done online in a few minutes, no matter who you each bank with.
Joint saving account
Save
Reach savings and financial goals together with our handy savings accounts.
Credit cards
convenience
Whether it's for everyday convenience, to be rewarded for your spend, or to manage your combined expenses, our credit cards have a range of features and benefits for your needs, like:
Insurance
Insurance
Protect your loved ones and your possessions with life, home, and car insurance.
CommBank Neo interest-free card
Credit card
An interest-free credit card with one simple monthly fee. No interest charges. No late fees. No international transaction fees. No surprise charges. Plus great benefits through CommBank Yello Cashback Offers5.
1 The earning and redemption of CommBank Awards points are subject to the CommBank Awards Program Terms & Conditions (PDF). Points are earned on eligible transactions (excludes for example BPAY transactions, cash advances, balance transfers and payments to the Australian Taxation Office unless made using a Business Awards card) and are subject to points capping. Awards and the number of points required for Awards are subject to change at any time without notice.
2 Cover is provided by XCover.com, a trading name of Cover Genius Pty Ltd (ABN 43 159 983 598, AFS Licence No. 490058), and underwritten by Allied World Assurance Company Ltd (ABN 54 163 304 907), for Commonwealth Bank of Australia (CBA). Limitations, exclusions (including for pre-existing medical conditions and persons aged 80 years or over) and eligibility criteria apply. You may need to upgrade your travel insurance in order to have a comprehensive or extended level of cover. Before acting on this information you should consider the appropriateness of the product with regard to your personal circumstances. See the Card Insurances Combined Product Disclosure Statement and Financial Service Guide and Card Travel Insurance Target Market Determination for details. Commonwealth Bank and its related bodies corporate do not issue or guarantee this insurance. It does not represent a deposit with or liability of either Commonwealth Bank or any of its related bodies corporate. We do not provide any advice on this insurance based on any consideration of your objectives, financial situation or needs. If you purchase an upgrade policy, we (Commonwealth Bank) receive a commission which is a percentage of your premium.
3 You won't be able to apply for an instalment plan if you don't meet our criteria (e.g. if you have exceeded your limit or if you are in default). Instalment plans are not available on CommBank Neo cards, non-Awards Business Cards, corporate cards or balance transfers.
The terms of the Credit Card Conditions of Use (PDF) relating to instalment plans (section 5) will apply.
While you have an instalment plan, we apply your credit card payments first to your current monthly instalments. This will apply even when you have other card balances with a higher interest rate, such as cash advances and purchases not on a plan.
Any interest-free period on purchases will no longer apply once the purchase is put on a plan.
You can cancel your instalment plan at any time. When a cancellation is processed, the outstanding instalment balance will be transferred to your purchases balance (or cash advance balance for cancelled cash advance plans) and accrue interest from the transfer date at the standard purchase or cash interest rate applicable on your account.
If you miss a monthly payment your plan won’t be cancelled and you can continue to make any remaining monthly payments due up to the end of your chosen term. However, if you miss an instalment payment, the unpaid amount will be transferred to your purchases balance (or cash advances balance if the instalment plan was a cash advance plan). It will then accrue interest at the purchases (or cash advance) rate.
4 Note that some types of transactions made via CommBank branches, telephone, online or mobile banking such as transfers to other accounts, bill payments, assisted cash withdrawals and transactions flagged as recurring (for example, direct debits) or that are not sent to us for authorisation won't be declined. For full terms and conditions of the spending cap, visit NetBank or the CommBank app. Other conditions apply.
The target market for these products will be found within the product’s Target Market Determination, available here.
Applications for credit cards are subject to credit approval. Full terms and conditions will be included in our Letter of Offer. Bank fees and charges apply. Please read our CommBank Credit Card Conditions of Use (PDF).
Full terms and conditions of the CommBank app are available on the app. The CommBank app is free to download however your mobile network provider charges you for accessing data on your phone. Find out about the minimum operating system requirements on the CommBank app page. NetBank access with NetCode SMS is required.
The advice on this website has been prepared without considering your objectives, financial situation or needs. Because of that, you should, before acting on the advice, consider its appropriateness to your circumstances. Please view our Financial Services Guide (PDF). Full terms and conditions for the transaction and savings accounts (PDF) mentioned and Electronic Banking (PDF) are available here or from any branch of the Commonwealth Bank.
Commonwealth Bank of Australia ABN 48 123 123 124 and Australian credit licence 234945.